Crypto Bot Trading and Taxes - Records You Need From Day One
Short answer: This is not tax advice - jurisdiction rules differ - but one fact is nearly universal: bots multiply taxable events, a grid bot can create hundreds of disposals per month, and the records the tax office expects have to exist before tax season. Export from day one.
This is not tax advice - jurisdiction rules differ, and they change. But one fact is nearly universal: bot activity multiplies taxable events, and the records you need have to exist before tax season. The US framework is the best-documented example of what most tax offices converge on, and this guide uses it as the reference model - with the caveat that your local rules are the ones that count.
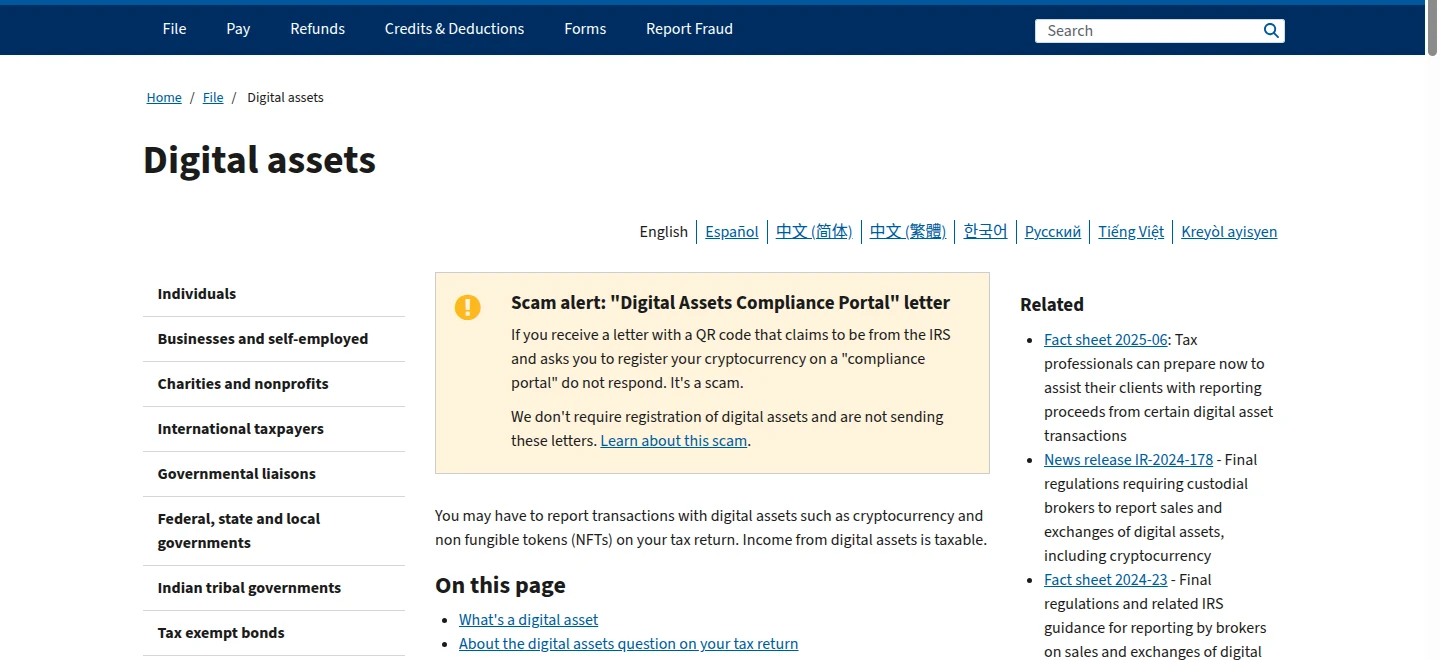
table of contents
Why bots change your tax profile
Under the reference framework, digital assets are property, not currency [1] - and trading property for other property is a disposal. That makes almost every bot action a reportable transaction:
- A grid round trip (buy, then sell) is one completed disposal with its own gain or loss.
- A DCA safety order creates a new lot with its own basis and holding period.
- A crypto-to-crypto exchange is a disposal on the currency you gave up, not just the cash-out at the end [2].
A grid bot can execute hundreds of round trips per month; a DCA bot creates dozens of small lots. Manual spreadsheets do not scale to that volume - the tax profile of bot trading is closer to day trading than to investing, with the record-keeping burden to match.
The records the reference framework expects
The IRS is unusually concrete about what "sufficient records" means: documentation of every purchase, receipt, sale, exchange or other disposition, plus the fair market value in US dollars at the time of each transaction [1]. Form 8949 is where the disposals land - one line per disposal, split into short-term and long-term boxes [3] - and the basis side has its own publication [5]. Fees count: the FAQ treats fees paid at purchase as part of basis and fees paid at sale as reducing proceeds [2].
One bot-specific detail decides everything: unit identification. If you do not specifically identify which units you sold, the default is FIFO - first in, first out [2]. Specific identification is allowed and documented (by transaction records showing acquisition date, basis and fair market value for each unit) [2] - but only if the records exist to support it.
What that choice is worth: a worked example
Here is the same disposal computed three ways on real BTC data [6]. Model: a grid-style bot accumulating $1,000 lots on every dip below its 7-day average through the 2024 April-September chop - 81 open lots by September, no cycle closes. Then one event: a partial sale of $2,000 on 2024-08-05 at the real daily close of $54,018.81, fees at 0.1% in both basis and proceeds [2]:
| Lot selection | Realized gain on the identical $2,000 disposal |
|---|---|
| FIFO (the default without records) | -$192.75 |
| HIFO - highest basis first (specific ID) | -$290.88 |
| LIFO - lowest basis last (specific ID) | -$17.55 |
Same trades, same prices, same disposal date: the taxable outcome swings by $273.33 purely on which lots the records let you select. The default (FIFO) is not necessarily the worst outcome - in a falling window it beat HIFO - but "whatever my records happen to support" is the only way to get the worst of both. Multiply the swing by every disposal a bot generates and the value of lot-level records stops being theoretical.
Exports that matter, before you commit to a platform
Before choosing a platform, check what it can export:
- Complete trade history in CSV or API form - the subscription platforms generally export; exchange-native bots export from the exchange itself.
- Monthly cadence - exchanges and platforms prune history over time; a retro-request for a year of trades can be slow or impossible. Monthly exports take minutes and are the entire discipline.
- Basis fields, not just proceeds - without acquisition cost data, your cost-basis rebuild becomes guesswork.
The platform comparison flags export quality where we have it documented; the cost calculator keeps the fee side honest, which is the other number the tax office cares about.
The 1099-DA reconciliation problem
Broker reporting has arrived: Form 1099-DA, "Digital Asset Proceeds From Broker Transactions", is the broker's copy of your disposals [4] - and the IRS receives the same copy you do. For bot traders this creates a reconciliation discipline the manual era never had: your bot platform's PnL numbers, your export's computed gains, and the broker's 1099-DA are three different systems looking at the same trades. Where they disagree, the IRS starts from the form it received. Your records exist to prove the difference, not to discover it in April.
Self-hosted discipline
Freqtrade and friends write local SQLite databases and logs - the project documents persistence through SQLite as a core feature [7], with configuration and dry-run state in local files [8]. That database is your source of truth: back it up with the same seriousness as the wallet it trades for. If you rebuild a server without backing up the database, your cost-basis rebuild becomes guesswork - and the FIFO default [2] silently applies to history you can no longer prove otherwise.
Holding periods are where bots quietly lose money
The reference framework taxes short-term holdings (one year or less) differently from long-term ones [2]. Buy-and-hold naturally accumulates long-term treatment; a bot that closes cycles in days or hours locks in short-term treatment on every round trip - a structural tax drag that compounds with the fee drag. That is not an argument against bots; it is an input the profit projection should include.
Note: This guide uses the US framework as the documented reference because it is the most explicitly published. If you trade from elsewhere, the shape is usually similar - disposals, basis, records - but rates, allowances and even the definition of a taxable event differ. Find local guidance; we do not provide tax advice.
The day-one checklist
- Enable every export your platform offers; calendar a monthly export.
- Keep the files somewhere you control - not only on the platform.
- Self-hosted: automate database backups with the same rigor as the bot itself [7].
- Log configuration changes - range changes, safety-order edits - so results stay interpretable when the tax year ends.
- Keep the records that would let you choose specific identification over FIFO [2], because you cannot reconstruct that choice retroactively - and the worked example above shows exactly what that choice is worth.
FAQ
Are bot trading profits taxable?
In most jurisdictions yes - in the US framework, digital assets are property, and each sale or exchange is a disposal reported whether or not it results in a gain [1]. Loss harvesting rules and holding-period effects vary; consult a local professional for your situation.
Does a bot trade count as a taxable event even between two cryptocurrencies?
Yes, under the US property framework - exchanging one virtual currency for another is a disposal with a capital gain or loss on the currency you gave up [2]. A grid bot swapping BTC for USDT and back creates two.
Which records does the tax office actually expect?
The IRS framework is explicit: records documenting receipts, sales, exchanges and other dispositions, plus the fair market value in dollars at the time of each transaction [1] - with the detail level required to specifically identify units if you want to choose rather than default to FIFO [2].
Do I get Form 1099-DA for bot trading?
Brokers report digital-asset proceeds on Form 1099-DA [4]. If your bot trades through an exchange, expect the exchange's copy to reach the IRS too - your own records must reconcile with it, and where the bot platform's numbers differ from the broker's, the broker's copy is the one the IRS sees.
Which platforms have the best trade exports?
The subscription platforms we review all export CSVs; exchange-native bots export from the exchange itself; self-hosted Freqtrade writes a local SQLite database that is your complete source of truth [7]. The reviews flag export quality where documented.
Why not just download everything in April?
Because exchanges and platforms prune history over time, and retro-requests can be slow or impossible. Monthly exports take minutes; a year of retro-fitted grid trades with missing basis data takes a very expensive accountant.
Sources
- IRS - Digital assets (property treatment, record requirements, scam alert) - verified live, screenshot in guide - accessed 2026-10-18
- IRS - FAQs on virtual currency transactions (property, basis incl. fees, holding period, FIFO default, specific identification with records) - accessed 2026-10-18
- IRS - Form 8949 instructions (per-disposal capital gain reporting, short/long boxes) - accessed 2026-10-18
- IRS - About Form 1099-DA, Digital Asset Proceeds From Broker Transactions - accessed 2026-10-18
- IRS Publication 551 - Basis of Assets (rev. 12/2025) - accessed 2026-10-18
- Binance Public Data - BTCUSDT daily klines (input for our worked example) - accessed 2026-10-18
- Freqtrade GitHub - open source bot with local SQLite persistence (self-hosted record keeping) - accessed 2026-10-18
- Freqtrade documentation - configuration and dry-run wallet (local config as source of truth) - accessed 2026-10-18