#1
Hummingbot
The open-source market-making framework - community-owned, 318 connectors, and the only bot line with institutional-grade pedigree.
Self-hosted Open source Free tier US ok
Price-gap capture between venues - slow, capital-heavy, and mostly not the easy money people imagine.
Short answer: Hummingbot is our top-rated arbitrage bot as of 2026-10-18 (8.1/10), free.
bots on this page: 8 · fully reviewed (active): 8 · free or with a free tier: 5 · need no third-party API keys: 4
quick picks
The open-source market-making framework - community-owned, 318 connectors, and the only bot line with institutional-grade pedigree.
Privacy-first desktop bot running locally on your machine, now on a single $29/month plan - the self-hosted sweet spot between Freqtrade's effort and cloud subscriptions.
Polished multi-exchange grid/DCA platform with 17 exchanges, 7-day no-card trial and solid support reputation.
Veteran cloud platform with a genuine free tier, AI strategy designer and the broadest copy-bot marketplace.
16 free built-in bots inside the exchange itself - zero subscription and no third-party API keys, at 0.05% per side.
The most established cloud bot platform - deep features, real API-key incident history, now OAuth-hardened.
Veteran platform with the deepest scripting (HaasScript) and a rare self-hosted TradeServer lane - power users only.
Free grid and DCA bots inside OKX Trading Bots - no third-party API keys, you pay only trading fees.
| Bot | Type | Price | Arbitrage | Backtest | Paper | Exchanges | US |
|---|---|---|---|---|---|---|---|
| Hummingbot | Self-hosted | free | yes | yes | yes | 50 | US |
| Gunbot | Self-hosted | $29/mo | yes | yes | yes | 20 | US |
| Bitsgap | Cloud platform | $23-149/mo | yes | yes | yes | 17 | US |
| Cryptohopper | Cloud platform | $29-129/mo | yes | yes | yes | 16 | US |
| Pionex | Exchange-native | 0.05% per trade | yes | - | - | - | US |
| 3Commas | Cloud platform | $15-140/mo | yes | yes | yes | 9 | US |
| HaasOnline | Cloud platform | $19.99-249.99/mo | yes | yes | yes | 24 | US |
| OKX Trading Bots | Exchange-native | free | yes | - | - | - | - |
Live values from our database - details and caveats in each review. "-" = not documented.
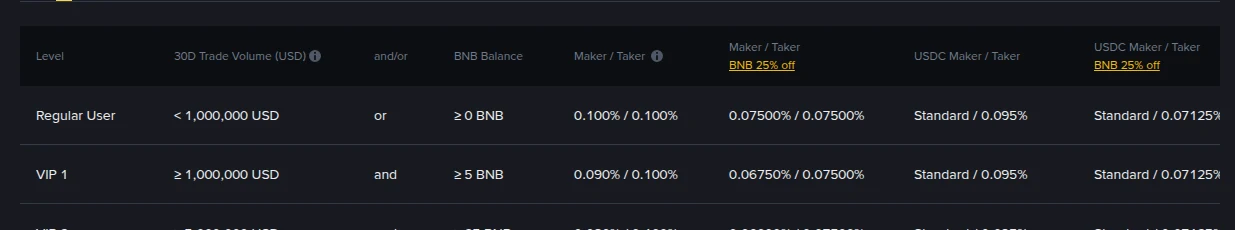
Arbitrage is the strategy whose marketing survives entirely on the first line of that chart. The honest version: a gap between venues is an invitation to a race you enter with retail infrastructure against desks with colocated servers, negotiated fee tiers and pre-positioned inventory[7]. The gap closes while you read about it.
That does not make the features useless - it makes them tools for a specific setup: meaningful capital split across venues, fee tiers that shave the per-trade cost (BNB discount moves Binance to 0.075%[4]), and the ops discipline to manage inventory across exchanges. The platforms on this page sell the automation; the setup is what determines whether it pays.
Cross-exchange (Bitsgap's spread model[1]): the intuitive one, and the transfer-bound one. Works best between venues with structurally different liquidity - and it must clear two fee schedules plus withdrawal costs per cycle.
Triangular (Cryptohopper's higher plans[2]): within one venue, no transfers, gaps measured in basis points and milliseconds[7]. On liquid BTC/ETH/USDT markets this is HFT territory; on thin pairs it is where retail sees "opportunities" that are really liquidity traps.
Market making (Hummingbot[6]): the professional's version of the same idea - quoted spreads on both sides, inventory-managed, no external transfers. Self-hosted, free, and as demanding as the self-hosted ops reality implies. If your interest is genuinely spread-shaped income, this is the lane that scales it honestly.
The version professionals run - and the version the cloud features approximate - pre-positions capital on both venues and never moves coins mid-trade. The operational reality behind the clean idea: capital splits (half idle at any moment by design), inventory drifts (the buying venue drains while the selling one fills), and rebalancing is itself a fee event that must be scheduled, sized and priced. Withdrawal fees and limits apply at rebalance; maintenance windows and withdrawal suspensions arrive exactly when spreads widen. None of this appears in feature lists because none of it is a feature - it is the job.
Add the venue risk dimension: pre-positioned inventory is unsecured exposure to both exchanges, and our /incidents/ timeline documents why that matters (Bybit 2025, Bitget 2026). Arbitrage capital is venue capital - the yield being chased competes with simply holding on a single regulated venue, which is a fair comparison the pitch never volunteers.
Peg deviations deserve their own paragraph because they generate the most seductive screenshots. A stablecoin trading at $0.97 looks like 3% for nothing; the honest reading is a 3% counterparty-risk quote - the market is pricing depeg or distress, and the "arbitrage" requires holding the instrument through exactly the event the discount prices. Routine peg noise (10-30 basis points) is smaller than the fee stack on most retail tiers[4]. The middle ground - small, persistent deviations on liquid pairs - belongs to the desks again.
The same logic scales to "arb" pitches that quote historical spreads: past gaps on dead pairs, screenshots without fee math, "proven" strategies with no methodology. The arbitrage vocabulary's history in this market is as a costume for fixed-return schemes[8] - which is why this page treats the honest version (capital-heavy, thin, operationally demanding) as the only one worth documenting.
If there is a defensible retail version, it is the boring one: two venues you already use, a pair with structural liquidity differences, inventory pre-positioned at sizes the position size calculator justifies, and a written rebalance rule. Run it on paper for a month, log every hypothetical fee and transfer, and let the ledger - not the screener - tell you whether the spread survives your stack. Most ledgers conclude the stack wins; that conclusion is worth $0 in subscriptions and a month of data. The rare exception - a structurally separated pair on venues you already fund - is exactly the kind of finding worth scaling slowly, one rebalance rule at a time. Document every cycle: entry spread, exit spread, fees both venues, transfer minutes. A month of that ledger is the only arbitrage curriculum that survives contact with real markets - and the cheapest tuition available.
For professionals with capital, fee tiers and speed - yes, thin and competitive. For retail, the gaps visible on free screeners are usually smaller than withdrawal fees, taker fees and slippage combined. The spreads that look like free money are the ones already being raced for in milliseconds[7].
Cross-exchange captures price gaps between venues - it pays transfer time or requires inventory on both sides. Triangular exploits inconsistencies within one exchange (BTC/ETH, ETH/USDT, BTC/USDT) - no transfers, but the gaps close in milliseconds on liquid venues[7], which puts retail against infrastructure.
Bitsgap automates spread arbitrage across its 17 connected venues from $23-29/mo[1]; Cryptohopper bundles exchange and triangular arbitrage into higher plans[2]; 3Commas lists it among features[3]; Hummingbot is the self-hosted specialist for maker-style spread capture[6].
The spread exists because price moved between venues; moving coins takes minutes and a withdrawal fee, and the gap closes before arrival. Inventory-model arbitrage (funds pre-positioned on both venues) avoids the transfer but splits capital and traps it - rebalancing still pays withdrawal fees when one side drains.
Enough that fees stay a small fraction of each trade and both venues' inventory is meaningful - practically, thousands of dollars pre-positioned per venue pair, at exchange fee tiers that reduce per-trade costs. Below that threshold, the stack in our figure eats the spread entirely.
Yes - "fixed, no-downside profits from price differences" is the classic pitch, and the FTC's marker covers it verbatim[8]. Real arbitrage is capital-intensive, latency-sensitive and thin; anyone selling it as easy money is selling the pitch, not the spread.
Less than directional strategies but not none: execution legs complete at different times (leg risk), spreads widen against you mid-trade, and inventory held on venues carries full market exposure between cycles.
Competition: professional desks run the same logic with colocated infrastructure, and gaps on liquid pairs close within milliseconds[7]. Retail-visible gaps concentrate in illiquid pairs - where withdrawal limits, spreads and rug risk live.
Peg deviations look like free money and usually are not - the large ones are crisis moments (exchange distress, depegs) where transfer and counterparty risk peak. The routine small deviations are smaller than fees. Treat stablecoin arb marketing with the same suspicion as any fixed-return pitch.
It is the honest one: an open-source framework for maker/spread strategies[6] with no subscription and no marketing - and the same unforgiving economics. If you can operate Hummingbot profitably, you did not need this page; if you cannot, the cloud arbitrage features will not bridge the gap.
Against the spread you can actually capture: subscription ($23-105/mo[1][2][3]) plus fees per trade[4] versus documented, testable spreads. The [bot cost calculator](/tools/bot-cost-calculator/) prices the subscription side; the screener data prices the rest - honestly, usually not in the feature's favor.